
A commercial property can appear ready for occupancy, acquisition, or refinancing while carrying six-figure liabilities behind the walls, above the ceiling grid, or beneath the parking lot. Property condition assessments give owners, investors, lenders, and occupiers a disciplined way to identify those liabilities before they affect a transaction, operating budget, or asset return.
For commercial real estate decision-makers, the assessment is not merely a checklist of visible defects. It is a business tool. It helps determine whether the purchase price reflects the property’s true condition, whether a lease obligation is reasonable, and whether a capital plan can support the investment thesis. The value lies in turning physical conditions into actionable financial decisions.
What a Property Condition Assessment Evaluates
A property condition assessment, often called a PCA, is a systematic review of a building and its major site components. The scope varies based on the property type, its age, the transaction, and the client’s objectives. A medical office building, industrial facility, bank branch, retail center, and multifamily asset do not carry the same operating risks.
Most assessments address the observable condition and remaining useful life of primary building systems. That commonly includes roofing, exterior walls, foundations, paving, drainage, HVAC equipment, electrical service, plumbing, fire and life-safety systems, elevators where applicable, and interior common areas. The reviewer also considers site conditions that can create substantial expense, including parking areas, sidewalks, retaining structures, lighting, landscaping, and stormwater controls.
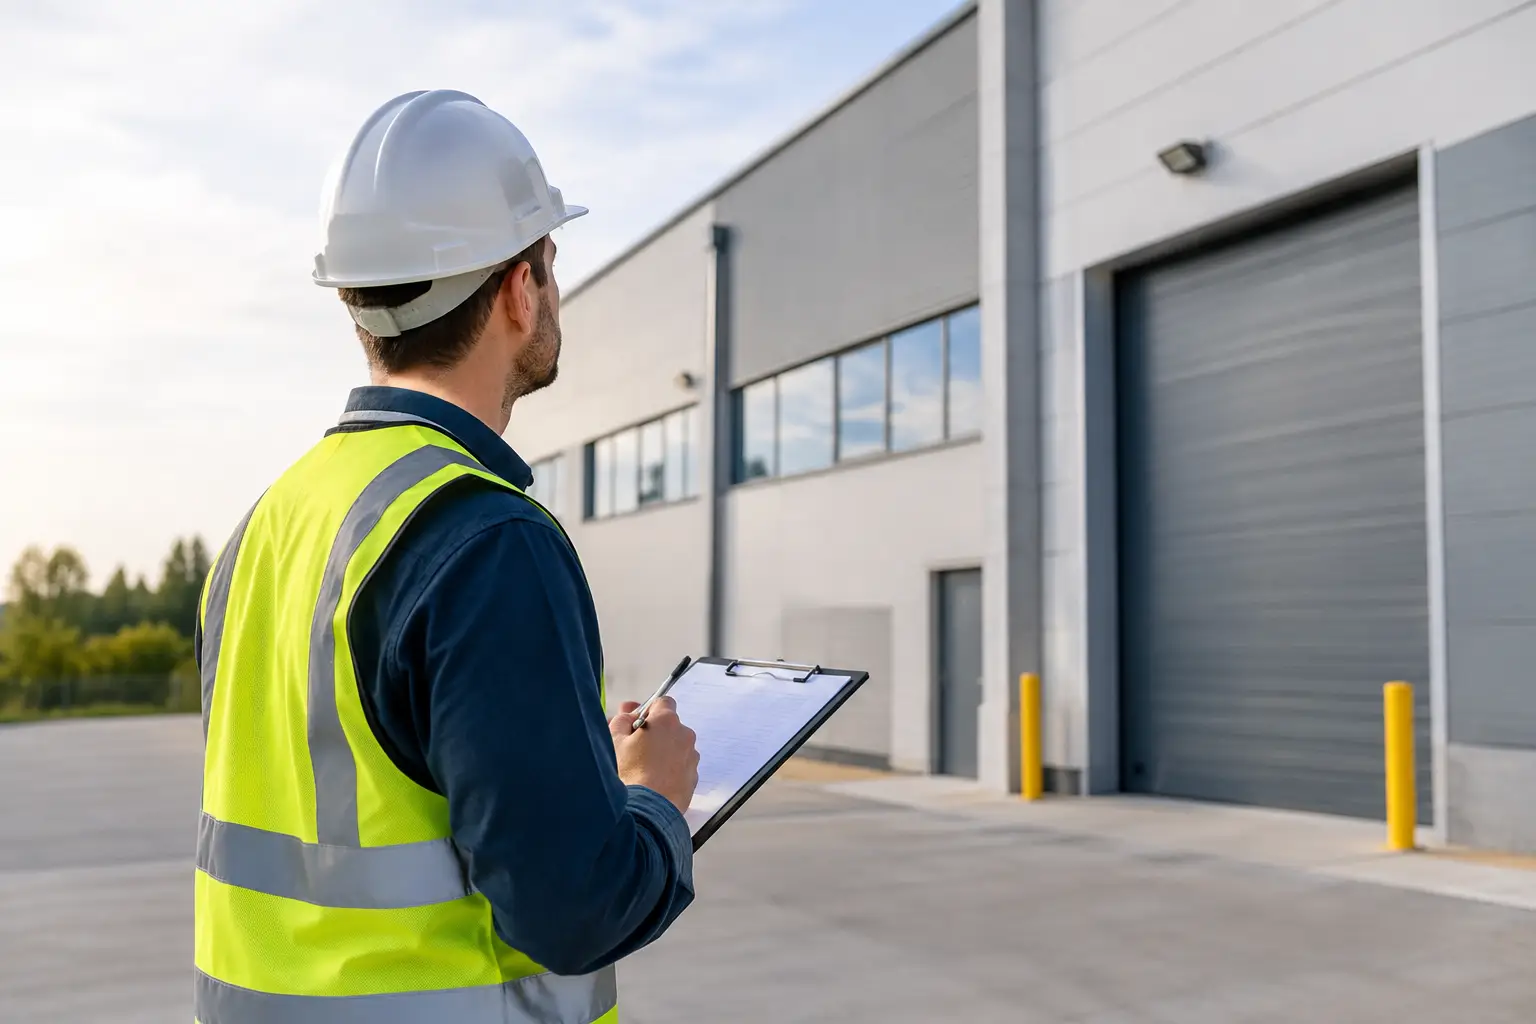
The process generally includes a site visit, review of available construction and maintenance records, interviews with property representatives when appropriate, and a written report. The report identifies deficiencies, distinguishes immediate repairs from anticipated future replacements, and provides cost opinions for recommended work.
A PCA is not a substitute for every specialized investigation. It may point to conditions that require further review by a structural engineer, roofing consultant, environmental professional, mechanical contractor, or code specialist. That distinction matters. The initial assessment identifies where the business risk may be concentrated so capital can be allocated to the right next step.
Why Property Condition Assessments Matter in Commercial Deals
The purchase price is only one component of an acquisition. A buyer who acquires a property at an attractive basis but inherits a failing roof, undersized electrical capacity, deferred pavement maintenance, and near-term HVAC replacements may find that projected returns disappear quickly.
Property condition assessments make those exposures visible during due diligence. A buyer can use the findings to renegotiate price, request seller repairs, establish an escrow, revise financing assumptions, or walk away when the condition risk exceeds the opportunity. Each response depends on market leverage and the strategic value of the asset. In a competitive acquisition, the ability to quantify risk early can be the difference between accepting a manageable capital plan and accepting an unknown liability.
For sellers, a pre-listing assessment can be equally valuable. It allows ownership to correct smaller deficiencies before they become negotiation points, organize maintenance documentation, and set more credible expectations with prospective buyers. A property that presents with clear records and a realistic capital story is often easier to underwrite.
Lenders and investors also rely on condition information to evaluate reserves and collateral risk. If a property requires substantial work in the next three to five years, the financing structure and investment distribution model should account for it. Deferring that conversation until after closing rarely improves the outcome.
The Difference Between Maintenance and Capital Risk
Not every deficiency deserves the same response. A damaged ceiling tile, failed door closer, or isolated landscaping issue may be a routine operating expense. A roof approaching the end of its service life, aging chiller equipment, deteriorated drainage, or recurring water intrusion is a capital planning issue.
This distinction affects both valuation and asset management. Routine maintenance supports tenant satisfaction and day-to-day operations. Capital expenditures protect the building’s long-term utility, marketability, and income-producing capacity. When ownership treats major replacements as isolated surprises rather than planned investments, operating performance becomes less predictable.
A useful assessment separates immediate life-safety or operational concerns from short-term repair needs and longer-range replacement obligations. That structure helps decision-makers build reserves instead of reacting to emergencies.
Using the Findings to Improve Returns
The assessment report should not sit in a due diligence file after closing. Its greatest value comes from integrating the findings into a practical ownership strategy.
First, align recommended work with the property’s business plan. An investor planning a five-year hold may prioritize repairs that protect occupancy, reduce operating interruptions, and preserve resale value. An owner-occupier may place greater emphasis on reliability, employee safety, client experience, and future expansion capacity. A developer evaluating a repositioning opportunity may need to decide whether existing systems can be retained or whether redevelopment economics are more realistic.
Second, convert costs into a capital schedule. A report may identify that the roof has several years of remaining life, while HVAC units need phased replacement sooner. Rather than treating the total projected cost as an immediate expense, ownership can schedule projects according to urgency, cash flow, warranty status, tenant needs, and seasonal considerations. A disciplined schedule supports more accurate budgeting and minimizes disruption.
Third, compare the repair plan against lease responsibilities. In net-leased and multi-tenant commercial properties, the allocation of maintenance and capital costs can be complicated. The lease may allow certain recoveries from tenants, limit pass-throughs, or place specific obligations on either party. Condition findings should be reviewed alongside lease language before a major expense is assumed to be recoverable.
Finally, use the assessment to guide vendor oversight. Repeated repairs to aging equipment may indicate that replacement is more economical than continued service calls. Conversely, a component with a limited but reliable remaining service life may not justify early replacement. The right answer depends on the cost of downtime, energy efficiency, tenant requirements, and ownership’s planned hold period.
Scope Must Match the Decision
A basic visual assessment may be sufficient for a newer, well-documented office property with a straightforward acquisition structure. It may not be sufficient for an older industrial building, a specialized medical facility, or a property with visible signs of structural movement, moisture intrusion, or utility limitations.
The more specialized the asset, the more important it is to define the assessment scope before the inspection. A distribution facility may require close attention to truck courts, dock equipment, clear heights, power capacity, and sprinkler design. A medical property may warrant additional review of emergency power, HVAC performance, accessibility, and infrastructure supporting clinical operations. Financial institutions may focus on security-related improvements, branch functionality, and deferred maintenance that could affect customer access.
Mississippi’s climate also makes exterior conditions particularly relevant. Heat, humidity, severe weather, heavy rain, and drainage performance can accelerate wear on roofs, mechanical systems, paving, and building envelopes. Local market knowledge helps ownership distinguish between ordinary aging and conditions likely to create recurring operational costs.
Common Mistakes That Weaken Due Diligence
The most costly mistake is ordering an assessment too late. If the inspection occurs just before the end of a contingency period, the buyer may not have enough time to obtain specialist opinions, secure repair pricing, or negotiate a meaningful resolution. Condition due diligence should begin early enough to influence the transaction.
Another mistake is focusing only on immediate repairs. A property can have few current deficiencies while still requiring major capital expenditures within the planned ownership period. Remaining useful life estimates are not perfect predictions, but they are essential for evaluating likely cash requirements.
Owners also weaken their position when they ignore records. Maintenance logs, repair invoices, warranties, permits, prior inspections, and equipment histories can clarify whether a problem is isolated or chronic. Good documentation can support a stronger sale process and better asset management. Missing documentation does not automatically mean a property is poorly maintained, but it increases uncertainty and should be reflected in underwriting.
A final mistake is treating the cost opinion as a fixed construction bid. Assessment costs are planning tools based on observed conditions and available information. Before committing to major work, obtain project-specific scopes and contractor pricing. The assessment provides direction; detailed design and bidding provide precision.
A Better Starting Point for Complex Assets
For a single-property owner, a PCA can establish a baseline maintenance and capital plan. For a portfolio owner, it can reveal where capital should be prioritized across multiple assets. For a corporate user, it can clarify whether an existing facility remains economically functional or whether relocation, expansion, or redevelopment should be considered.
Mark S Bounds Realty Partners approaches commercial real estate as an operating and investment asset, not simply a transaction. Condition information becomes more valuable when considered alongside market position, lease structure, valuation, operating costs, and long-term ownership objectives.
The most productive question is not, “What is wrong with this building?” It is, “What will this property require to support the return, operations, and exit strategy we expect?” A well-timed property condition assessment gives decision-makers the facts to answer that question before the cost becomes unavoidable.